

Here at Shuman Legal, we’re dedicated to making sure the knowledge of these complicated situations is easily accessible and understandable.
Illinois has specific rules governing total-loss settlements under your own auto insurance policy. Different rules and legal theories may apply when you are seeking property-damage compensation solely from another driver’s liability insurer.
That’s why we’ve created a guide to help you understand everything you need to know about calculating the total loss value of your car works.
Your Search for Help Ends Here.
Get FREE Legal Advice Now!
 Book Consult
 Call Now
The minute you sign with Shuman Legal® – we start working.
How Insurers Decide a Car Is Totaled
Whether you’ve been in a fender-bender, rear-ended at a stop light, or backed into, typically, an insurance company is going to have to evaluate the damage and the cost to fix it. This can always vary depending on many different factors, including the age of your vehicle and its resale value.
Insurance companies usually use two methods, depending on your state:
- Threshold Method:
If repairs cost more than a fixed percentage of the car’s market value (typically 60–80%), it qualifies as totaled.
- Total Loss Formula:
This is where calculations can get complicated. Typically, how this formula works is by calculating repair cost + salvage value and comparing it with the actual cash value, which is what your car was worth before the accident. If the result shows that the repair cost and salvage value exceed what the car is worth, it is totaled.
- Method for Calculation in Illinois
The state of Illinois may use the “Formula Method,” which also means there is no legal threshold. This gives a leg-up for insurance companies as it gives them more flexibility because there is no strict percentage. In other surrounding states for contrast, Indiana, Iowa, and Wisconsin all have a legal threshold of 70%.
| State | Method | Legal Threshold |
| Illinois | Total Loss Formula | No legal % for standard claims (70% for some salvage titles) |
| Indiana | Threshold | 70% |
| Iowa | Threshold | 70% |
| Wisconsin | Threshold | 70% |
| Missouri | Threshold | 80% |
Illinois does not impose a single percentage threshold that requires an insurance company to declare an ordinary insured vehicle a total loss. Insurers may consider repair costs, vehicle value, expected supplemental damage, salvage value, and policy terms when making that decision. Once your insurer determines that your vehicle is a total loss, Illinois regulations govern how a first-party cash settlement or replacement must be valued.
Insurers can also sometimes use a lower threshold than state law requires, as they can declare your car totaled even if the repair bill does not actually hit the limit of Illinois’ Total Loss Formula. This is their safety buffer, because insurance companies want to avoid situations where shops end up finding hidden damage that will cost them a lot more than calculated, but work has already begun on the car.
Say you have a hairline fracture in the frame that cannot be seen until some parts of the body have been taken apart; that qualifies as hidden and supplemental damage. In order for it to be fixed, safe, and restored to pre-loss condition, the repair cost will be greatly increased.
Most shops rely on estimating their costs for repairs because of situations like this. An inspection often doesn’t tell the true story of how hard a vehicle was hit.
Your Search for Help Ends Here.
Get FREE Legal Advice Now!
An experienced Car Accident Lawyer knows what needs to be done. The minute you sign with Shuman Legal® – we start working.
What Your Car Is Actually Worth (ACV)
For a lot of Americans, your car can feel like an extension of your independence. It gets you where you need or want to go every day, whether that be work, school, or date night. When an incident occurs where you need to know the actual cash value (ACV) of your vehicle, this can be the most common point of conflict in a total loss claim. It’s important to understand how the insurers are getting their number, so you or your lawyer can ensure it is an accurate one.
For an Illinois first-party total-loss claim, the insurer generally determines your vehicle’s pre-loss retail market value using approved valuation sources. The valuation should account for factors such as your vehicle’s make, model, options, mileage, condition, and relevant local market data. This means insurers do not take into consideration what you paid for it, and if you have an outstanding loan for your car, you may owe more than you get back, depending on your coverage.
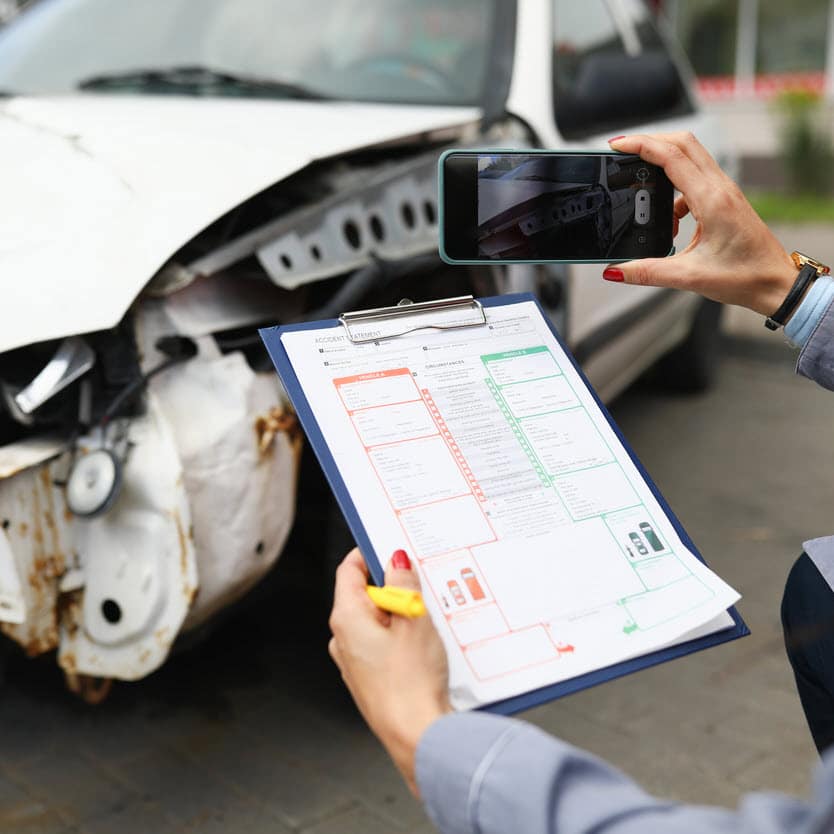 How Insurers calculate ACV: Insurers often use third-party software to find vehicle sales comparable to how your vehicle was right before the incident, which can include Kelly Blue Book and NADA guides, as well as details such as mileage, condition, and features. The details involving the condition of your vehicle are important. If an insurer does not properly calculate the details, such as putting in a lower incorrect trim level, this can impact the number negatively.
How to check their math yourself:
Insurers can undervalue vehicles often because their automated systems can undermine the condition of your vehicle. Documentation can be your leverage.
- Collect your maintenance records and receipts, including upgrades and ensure they factored in the documentation.
- Research what similar vehicles are actually selling for. Popular resale sites such as Autotrader or Cargurus allow you to filter through and search for your exact vehicle. Include your location, year, make, model, and mileage. This will be valuable if you find cars listed much higher than they stated.
- Check if you have photos of your car right before the accident. This documents the condition so there is no confusion. This includes interior photos as well, and thorough exterior ones. The more photos, the stronger your evidence.
Repair Costs and Salvage Value
The insurance adjuster provides an initial estimate, but to them, this is just another day’s work that can be impersonal. To you, this is your car you likely relied on every single day. If you want to be certain their estimates are accurate, you should shop around.
- To properly estimate repair costs, get multiple estimates from body shops around you. If damage affects more than just the body of the vehicle, they may refer you to a mechanic shop to get a quote from as well.
- Salvage value is defined by what a salvage yard would pay for your vehicle, as is after the accident. This matters for two reasons:
- It’s a factor within the total loss formula calculation (cost of repair + salvage value).
- If you want to keep your totaled car, the insurance company deducts the salvage value from your payout. You would only receive what the car is worth, but not what the salvage yard would give you for it. This is not allowed in some states or circumstances. In Illinois, you cannot keep a totaled car unless it is 9 years or older.
H2: Running the Numbers: Total Loss Calculators
All of these factors can be difficult to calculate manually. There are calculators online where you can plug in ACV, repair cost, and salvage value to see how your situation stacks up under your state’s rules. The insurer makes the initial total-loss and valuation decision, but you do not necessarily have to accept its valuation. Illinois regulations provide additional rights in some first-party claims, including procedures for challenging a valuation when you cannot purchase a comparable vehicle for the amount offered.
Here’s a sample calculation showing how both methods play out with real numbers.
| Method | The Math | The Result |
| 70% Threshold (Other States) | The repair cost is $6,500, is this more than 70% of the value ($7,500)? | REPAIR (The repairs are “cheap” enough) |
| Total Loss Formula | Is $6,500 (Repair cost) + $4,000 (Salvage value) more than the car’s value of $10,000? | TOTALED (The total is $10,500) |
What Else Affects the Decision
Multiple factors can affect the numbers. Insurance companies tend to look at the big picture.
Here are some of those factors:
- Your insurance policy terms and state laws. For example, if the damage was caused by flooding, total loss thresholds can be much lower than the standard.
- Vehicle age and model, some states have different laws based on the age of your car.
- Insurance adjusters look for red flags that indicate the car could never be restored to pre-loss condition. Depending on how bad the damage is, there can be hidden damage underneath that can cost them more money that they’ll be scared of being forced into paying down the route of restoration.
- There could be a lot of part shortages depending on your vehicle. In recent years, rising repair costs and parts shortages have pushed total loss rates up significantly.
Which Insurance Coverage Actually Pays
When you choose an insurance policy, there are a lot of different factors you may pay coverage for. Especially If you have multiple insurers or types of coverage. This depends on what you chose when you first got your policy, as mandates vary state by state.
- Collision: Generally pays for covered collision damage to your insured vehicle regardless of who caused the crash, subject to your deductible and policy terms.
- Comprehensive: Covers your car if damage occurred due to non-collision incidents, such as theft, natural disasters, hail, or hitting an animal that caused damage, like a deer.
- Property damage liability: If you caused damage to another person’s property/vehicle, this covers the damage you caused.
- Uninsured/Underinsured: If an at-fault driver has too little of coverage to cover damages, or none at all, this covers you and your vehicle, if you purchased that coverage type and its requirements are satisfied.
- Liability-only policy: If you selected bare-minimum coverage, such as a liability-only policy, then your policy only covers damage you do to others vehicles. It does not cover your own vehicle. At all.
There are nuances to each case. This can include things like If you have a loan, then the payout goes to the lender first. If the payout is less than what you owe, you cover the gap unless you have gap insurance, which is exactly what it sounds like.
What to Do After Your Car Is Damaged
The aftermath of an accident can be overwhelming, especially if it’s bad enough where the car might be totaled.
Follow these steps to make sure you get the proper compensation you’re entitled to:
- File the insurance claim as soon as possible, and schedule an inspection.
- Insurance will want photos. Take as many as possible. You’ll want to gather photos of your car from before the incident too, as well as maintenance records, and police reports.
- Research what your car is actually worth before accepting anything. Take advantage of online marketplaces to search through, and take into consideration your location, any upgrades and trim level.
- Contact your lender if you’re financing. Make sure you won’t owe more than the car is worth, and check if you have gap coverage in your insurance plan if you might.
- Review the offer and push back if it’s low. Don’t be afraid to ask the insurer questions, and for their valuation report to see the compared cars.
- If you’re negotiating, provide comparable sales data from your research, or get an independent appraisal.
- Decide what to do with the car:
- If you take the payout and walk away: You’ll sign the title over to the insurance, and they will give you a check for the car’s value, minus your deductible. The car will be towed to a salvage yard.
- If you keep the car: You get a reduced payout, a salvaged title, and you can’t legally drive the car until it’s repaired and reinspected up to state standards. If it’s repaired and passes inspection, you apply for a rebuilt title. This may not be an option depending on your state laws and how old the car is.
For qualifying first-party cash settlements in Illinois, if you purchase or lease another vehicle within 30 days after receiving the settlement, your insurer generally must reimburse applicable sales tax and transfer and title fees, subject to the statutory limits. You generally must provide documentation of the purchase and those expenses within 33 days after receiving the settlement unless the insurer pays those amounts at settlement. If you miss this small window and don’t send the bill of sale to your insurance company, they do not have to pay you back.
When It’s Worth Talking to a Lawyer
There can be a lot of nuances depending on your situation. Negotiating a total loss claim can be exhausting. If you were injured and your car may be totaled, this can be even more difficult to navigate.
An attorney can review your policy, challenge an undervalued ACV, dispute the repair estimate, and handle any injury claims from the same accident. Insurance companies often prioritize minimizing payouts. So if the insurer is lowballing you and you can’t get traction negotiating on your own, this is when professional help pays off.
FAQs
- ACV vs. replacement cost: what’s the difference?
Actual cash value (ACV) is what your car would be worth in a marketplace right before the crash; this includes depreciation. Replacement cost is what it would cost to buy your car today as a brand-new version, not including depreciation.
- Can I keep my totaled car?
This depends on the state you reside in. In Illinois, you can only keep your totaled car if it is over 9 years old, or the damage is only cosmetic, such as hail damage. Your title will be labeled as salvaged, and depending on your situation, it can be a lot of work and legal hoops to restore it to a drivable rebuilt title.
- How long does this process take?
It typically takes 5 to 10 business days for an insurance company to officially declare a total loss on your vehicle. If you accept the settlement and sign the paperwork, you will receive your check from insurance within 1 to 7 business days from signing. If there are any disputes, missing reports or just a more complex situation, the process can stretch out to over a month. Remember, these are all just rough estimates and situations can vary case to case.
- Do I actually need a lawyer for a property damage claim?
This depends. If you are not injured and you think the insurance company’s offer is fair, you can likely handle it yourself. If the situation is more complex or if the insurer is lowballing you, being stubborn, or acting in bad faith, then a lawyer could be an immense help in getting you the proper compensation. At Shuman Legal, we offer free consultations if you’re unsure. With just a quick phone call, you can gain clarity at no cost to you.